
Cash offers within 24 hours for Tulsa homes
If you have gotten a foreclosure notice from Tulsa County District Court, inherited a house on the North Side you cannot afford to hold, or sat through two failed agent listings because of foundation cracks from Oklahoma clay — we can have an offer to you within 24 hours. Cash, as-is, no repairs, no commission. You pick the closing date.
Short version: Cash offer within 24 hours. Close in 7–14 days. No repairs, no agent commission, no closing costs on our side. Oklahoma’s judicial foreclosure process takes 4–9 months before the courthouse steps — you usually have time to sell, but not unlimited time.
What actually sells to a cash buyer in Tulsa
Not every Tulsa home belongs in a cash sale. Here is a plain breakdown.
| Situation | Agent listing | Cash buyer |
|---|---|---|
| Good condition, 60+ days available | Almost always better — you keep the difference | Takes a discount for speed you don’t need |
| Foundation movement from clay soil | Appraiser flags it; financed buyers exit | We price it in and close |
| Foreclosure notice in hand | May work with 60+ days before the sale date | Closes before the courthouse date |
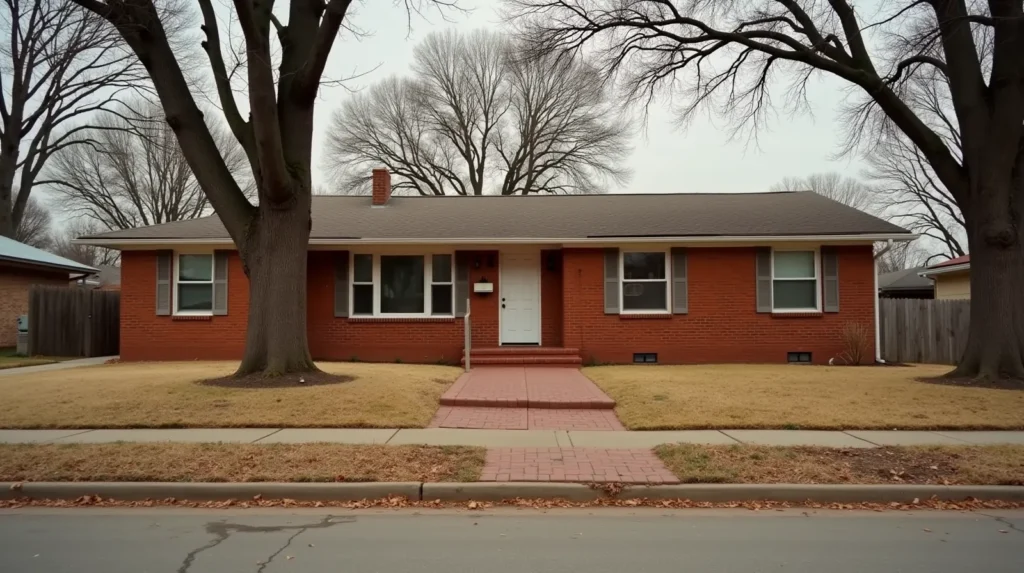
| Inherited house, North Tulsa, deferred maintenance | Repair costs eat the margin on $90k homes | As-is, no repairs, no commission math problem |
| Pre-1970 stock with aging electrical or plumbing | FHA/VA appraiser flags it; financed deals die | No appraisal requirement |
| Energy-sector job loss, mortgage falling behind | 45–90 day listing may not fit the window | 7–14 day close possible |
Oklahoma’s foreclosure process — the actual timeline
Oklahoma runs judicial foreclosures. The lender files a petition at Tulsa County District Court (500 S. Denver Ave.), you’re served and have 20 days to respond, and the court eventually orders a sheriff’s sale. Published notice runs four consecutive weeks in a Tulsa County legal newspaper before the sale date. From missed payment to courthouse steps, the realistic window is 4–9 months.
Under Oklahoma Statutes Title 12, § 686 et seq., once the sale happens and you haven’t made a deal, the lender gets a sheriff’s deed. Oklahoma also has a 6-month post-sale redemption period under § 700 — but redeeming means paying the full purchase price plus interest. Most sellers facing foreclosure cannot do that. Selling before the sale stops the process completely: the lender is paid off at closing, any surplus is yours, and the foreclosure never appears on your credit report as a completed event.
The specific clock depends on how backlogged Tulsa County’s civil docket is. Some cases resolve in 4 months; a contested filing with a loaded court can stretch to 9. What you know for certain is the date on the notice and the date the lender filed. A call costs nothing, and it tells you whether there’s time to close before the sale is scheduled.
Why North Tulsa and East Tulsa homes end up needing a cash buyer
North Tulsa — from downtown north through neighborhoods like Mohawk Park, the blocks around Admiral Place, and the streets near Pine Street — has significant housing stock from the 1940s through 1970s. That era in Oklahoma means original 60-amp fuse boxes or early 100-amp panels, galvanized supply lines, 3-tab roofs from the 1990s past their service life, and HVAC systems running 20 or more years beyond the standard replacement window.
FHA and VA appraisers are required under HUD Handbook 4000.1 to flag each of those as conditions requiring repair before the lender funds. If the seller cannot repair — because they’re behind on payments, because the repair exceeds the home’s value, because the estate has no money — the financed buyer exits. Cash buyers don’t use an appraiser, so those conditions don’t become deal-killers.
East Tulsa, along the Route 66/11th Street corridor and into the Kendall-Whittier and Lansing neighborhoods, has similar stock at similar price points. North Tulsa homes priced in the $75k–$130k range face a particular math problem: a 5–6% agent commission on a $100,000 sale is $5,000–$6,000. Add $15,000 in repairs to pass an FHA inspection, closing cost credits a buyer will demand, and 60 days of carrying costs, and the seller’s net on a home with equity can go to near zero. A cash offer at $82,000, no repairs, no commission, no credits, often nets the same or more.
Oklahoma clay soil and the foundation problem
Tulsa County’s expansive red clay swells when it rains and contracts in drought. For a pier-and-beam house from 1958, 60 years of that movement shows up as stair-step cracks in brick veneer, interior doors that drag in humid weather, floors that slope toward the center, and in serious cases, visible gaps at the foundation line on the side of the house that dries fastest in summer.
An appraiser who observes foundation movement issues a repair condition. Structural engineering reports run $400–$800. Pier repair starts around $5,000 and can reach $30,000 or more depending on scope. For a home priced at $110,000, those numbers change the calculation entirely. Cash buyers price the repair cost into the offer rather than asking for it as a condition.
This is the most common reason we hear about a failed agent listing in Tulsa: two buyers walked after inspection. Foundation movement caught by an inspector triggers a lender’s appraiser review, which becomes a condition, which the seller cannot meet. Cash transaction — no appraiser, no lender, no inspector trigger.
When you should not sell to us
If the house is updated and you have 60 days or more, list with a Tulsa agent. We say this because it’s true, and a seller who belongs on the MLS is not our customer.
Homes in the Maple Ridge Historic District, Brookside along the Peoria corridor, Midtown near Cherry Street, or South Tulsa neighborhoods south of 71st Street — especially east of Yale — in good working condition should go to the open market. The gap between a cash offer and a listed price on a well-maintained Brookside bungalow can be $25,000 or more. That’s real money worth capturing through a traditional sale.
Cash buyers make sense when: the repair list is too long or too expensive to finance, there’s a deadline that cannot move (foreclosure auction, probate order, PCS transfer out of the American Airlines MRO facility on the east side or one of the energy firms), the price point makes agent math fail, or the house has a problem that will kill a financed deal at the appraisal stage.
Arkansas River floodplain
Sections of West Tulsa and neighborhoods along Riverside Drive near the Arkansas River sit in FEMA-designated AE or AO flood zones. Properties in those zones require National Flood Insurance Program coverage (42 U.S.C. § 4012a) as a condition of any federally-backed mortgage — typically $3,000–$8,000 per year on affected Tulsa properties. That cost removes some buyers from the pool entirely. Cash buyers have no mandatory flood insurance requirement.
Straight answers
How long does a Tulsa cash sale actually take?
7–14 days from offer acceptance in most cases. The main variable is the title company’s schedule and whether any liens — property tax liens, hospital liens, HOA liens — need to clear first. We’re not the bottleneck; the title process is.
Do you buy in Broken Arrow and Owasso?
Yes. We work throughout the Tulsa metro, including Broken Arrow and Owasso. The process is the same regardless of which county the property is in. See the Oklahoma overview if you’re outside the metro.
I’ve missed a payment. Is it too late?
No. Oklahoma judicial foreclosure runs 4–9 months before the courthouse sale. One or two missed payments puts you early in the process. Call (615) 780-7349, tell us what the notice says, and we’ll tell you honestly whether there’s time to close before the sale date.
What if the foundation has real problems?
We buy houses with Oklahoma clay-soil foundation issues. We’ll ask to see any engineering reports you have, or we’ll walk the property and make an offer based on the actual repair scope — not a generic discount. Submit the address below.
Does the house need to be vacant?
No. You can be living there through closing. We work around your move-out timeline.
Ready for a number? Call (615) 780-7349 or put the address in below. Offer within 24 hours, no obligation. If foreclosure is the issue, that page covers the full mechanics of selling before the auction. If it’s an inherited or probate property, that page covers those specifics.
Keep reading
- Sell My House Fast in Knoxville, TN
- We Buy Houses in Minnesota
- Sell My House Fast Kansas City MO
- Sell My House Fast in Carmel IN — Cash Offer in 24 Hours
- Selling an Inherited House: What Most Heirs Don’t Know
- Sell My House Fast in Milwaukee, WI
Ready for a number? Get your cash offer or call (615) 780-7349.